InvestingActivitiesAcquire productiveresources such asproperty, plant,equipment,technology, etc. tooperate the business AICPA CodeofProfessionalConductSix principles that expressthe basic tenets of ethicaland professional conductand call for an unswervingcommitment to honorablebehavior, even at thesacrifice of personaladvantageIncomeStatementMeasures andreports thefinancial resultsof a firm’sperformanceIndependentAuditorsIndependent experts inaccounting who carefullyevaluate a company’saccounting records andverify whether the financialstatements are fairlypresented in accordancewith professionalstandards.FinancingActivitiesRaise equity capitalby attractinginvestments frombusiness owners oracquire resourcesfrom lenders AccountingStandardsUpdateA newlyreleasedstandardby FASBAccountingStandardsCodificationElectronic databasethat integrates andtopically organizesU.S. GAAP into onecoherent body ofliteratureAssetsResourcesof the firmForm10-KAnnual reportincluding financialstatements filed bypublicly tradedcompaniesDueCareA member should observethe profession’s technicaland ethical standards,strive continually toimprove competence andthe quality of services, anddischarge professionalresponsibility to the best ofthe member’s ability.FinancialReportingProcessCommunicatingfinancial accountinginformation toexisting and potentialinvestors, creditors,lenders, and otherexternal decisionmakersOperatingActivitiesUtilize resourcesin day-to-dayactivities toproduce goodsand/or servicesand sell them tocustomersContributedCapitalAmountsinitiallycontributedbyshareholdersStatement ofShareholders'EquityProvides informationabout the commonshareholders’ equityclaims on thecompany and howthose claims changeduring the periodBalanceSheetA snapshot ofthe resourcesof a firm andthe claims onthe firmNotes toFinancialStatementsExplains how theaccounts and amountshave been determined.Provides importantdetails about theaccounting principles,methods, andestimates the companyhas used.Statementof CashFlowsCash inflowsand outflowsfrom operating,investing andfinancingactivitiesThePublicInterestMembers should actin a way that willserve the publicinterest, honor thepublic trust, anddemonstratecommitment toprofessionalism.IntegrityMembers shouldperform allprofessionalresponsibilitieswith the highestsense of integrity.Scope &Nature ofServicesA member in publicpractice shouldobserve thePrinciples of the CPCin determining thescope and nature ofservices to beprovidedComprehensiveIncomeChange in equity of acompany during aperiod fromtransactions, events,and circumstancesrelating to nonownersourcesAccountingStandardsUsed to measureand reportfinancialstatements thatare relevant andrepresentationallyfaithfulStakeholdersCreditors,Investors,Employees,Suppliers,Governments,CommunitiesFASBEstablishesGAAPManagementDiscussion &AnalysisExtensivenarrativediscussion andquantitativeanalysis from thecompany’smanagers.IFRSInternationalFinancialReportingStandardsResponsibilitiesMembers shouldexercise sensitiveprofessional andmoral judgmentsin their activities.NetIncomeRevenues –Expenses +Gains –LossesSecuritiesandExchangeCommission(SEC)Has legal authority toprescribe accountingprinciples andreporting practices forall corporations issuingpublicly tradedsecurities within theU.S. capital markets.Objectivity &IndependenceA member shouldbe objective andfree from conflictsof interest indischargingprofessionalresponsibilitiesIASBInternationalAccountingStandardsBoardAccountingEquationAssets =Liabilities +Shareholders’EquityEmergingIssuesTaskForceIdentify significantemergingaccounting issuesthat it feels theFASB shouldaddress.GAAPGenerallyAcceptedAccountingPrinciplesInvestingActivitiesAcquire productiveresources such asproperty, plant,equipment,technology, etc. tooperate the business AICPA CodeofProfessionalConductSix principles that expressthe basic tenets of ethicaland professional conductand call for an unswervingcommitment to honorablebehavior, even at thesacrifice of personaladvantageIncomeStatementMeasures andreports thefinancial resultsof a firm’sperformanceIndependentAuditorsIndependent experts inaccounting who carefullyevaluate a company’saccounting records andverify whether the financialstatements are fairlypresented in accordancewith professionalstandards.FinancingActivitiesRaise equity capitalby attractinginvestments frombusiness owners oracquire resourcesfrom lenders AccountingStandardsUpdateA newlyreleasedstandardby FASBAccountingStandardsCodificationElectronic databasethat integrates andtopically organizesU.S. GAAP into onecoherent body ofliteratureAssetsResourcesof the firmForm10-KAnnual reportincluding financialstatements filed bypublicly tradedcompaniesDueCareA member should observethe profession’s technicaland ethical standards,strive continually toimprove competence andthe quality of services, anddischarge professionalresponsibility to the best ofthe member’s ability.FinancialReportingProcessCommunicatingfinancial accountinginformation toexisting and potentialinvestors, creditors,lenders, and otherexternal decisionmakersOperatingActivitiesUtilize resourcesin day-to-dayactivities toproduce goodsand/or servicesand sell them tocustomersContributedCapitalAmountsinitiallycontributedbyshareholdersStatement ofShareholders'EquityProvides informationabout the commonshareholders’ equityclaims on thecompany and howthose claims changeduring the periodBalanceSheetA snapshot ofthe resourcesof a firm andthe claims onthe firmNotes toFinancialStatementsExplains how theaccounts and amountshave been determined.Provides importantdetails about theaccounting principles,methods, andestimates the companyhas used.Statementof CashFlowsCash inflowsand outflowsfrom operating,investing andfinancingactivitiesThePublicInterestMembers should actin a way that willserve the publicinterest, honor thepublic trust, anddemonstratecommitment toprofessionalism.IntegrityMembers shouldperform allprofessionalresponsibilitieswith the highestsense of integrity.Scope &Nature ofServicesA member in publicpractice shouldobserve thePrinciples of the CPCin determining thescope and nature ofservices to beprovidedComprehensiveIncomeChange in equity of acompany during aperiod fromtransactions, events,and circumstancesrelating to nonownersourcesAccountingStandardsUsed to measureand reportfinancialstatements thatare relevant andrepresentationallyfaithfulStakeholdersCreditors,Investors,Employees,Suppliers,Governments,CommunitiesFASBEstablishesGAAPManagementDiscussion &AnalysisExtensivenarrativediscussion andquantitativeanalysis from thecompany’smanagers.IFRSInternationalFinancialReportingStandardsResponsibilitiesMembers shouldexercise sensitiveprofessional andmoral judgmentsin their activities.NetIncomeRevenues –Expenses +Gains –LossesSecuritiesandExchangeCommission(SEC)Has legal authority toprescribe accountingprinciples andreporting practices forall corporations issuingpublicly tradedsecurities within theU.S. capital markets.Objectivity &IndependenceA member shouldbe objective andfree from conflictsof interest indischargingprofessionalresponsibilitiesIASBInternationalAccountingStandardsBoardAccountingEquationAssets =Liabilities +Shareholders’EquityEmergingIssuesTaskForceIdentify significantemergingaccounting issuesthat it feels theFASB shouldaddress.GAAPGenerallyAcceptedAccountingPrinciples

Chapter 1 - The Demand for and Supply of Financial Accounting Information - Call List

(Print) Use this randomly generated list as your call list when playing the game. There is no need to say the BINGO column name. Place some kind of mark (like an X, a checkmark, a dot, tally mark, etc) on each cell as you announce it, to keep track. You can also cut out each item, place them in a bag and pull words from the bag.


1
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
25
26
27
28
29
30
31
32
33
34
  1. Acquire productive resources such as property, plant, equipment, technology, etc. to operate the business
    Investing Activities
  2. Six principles that express the basic tenets of ethical and professional conduct and call for an unswerving commitment to honorable behavior, even at the sacrifice of personal advantage
    AICPA Code of Professional Conduct
  3. Measures and reports the financial results of a firm’s performance
    Income Statement
  4. Independent experts in accounting who carefully evaluate a company’s accounting records and verify whether the financial statements are fairly presented in accordance with professional standards.
    Independent Auditors
  5. Raise equity capital by attracting investments from business owners or acquire resources from lenders
    Financing Activities
  6. A newly released standard by FASB
    Accounting Standards Update
  7. Electronic database that integrates and topically organizes U.S. GAAP into one coherent body of literature
    Accounting Standards Codification
  8. Resources of the firm
    Assets
  9. Annual report including financial statements filed by publicly traded companies
    Form 10-K
  10. A member should observe the profession’s technical and ethical standards, strive continually to improve competence and the quality of services, and discharge professional responsibility to the best of the member’s ability.
    Due Care
  11. Communicating financial accounting information to existing and potential investors, creditors, lenders, and other external decision makers
    Financial Reporting Process
  12. Utilize resources in day-to-day activities to produce goods and/or services and sell them to customers
    Operating Activities
  13. Amounts initially contributed by shareholders
    Contributed Capital
  14. Provides information about the common shareholders’ equity claims on the company and how those claims change during the period
    Statement of Shareholders' Equity
  15. A snapshot of the resources of a firm and the claims on the firm
    Balance Sheet
  16. Explains how the accounts and amounts have been determined. Provides important details about the accounting principles, methods, and estimates the company has used.
    Notes to Financial Statements
  17. Cash inflows and outflows from operating, investing and financing activities
    Statement of Cash Flows
  18. Members should act in a way that will serve the public interest, honor the public trust, and demonstrate commitment to professionalism.
    The Public Interest
  19. Members should perform all professional responsibilities with the highest sense of integrity.
    Integrity
  20. A member in public practice should observe the Principles of the CPC in determining the scope and nature of services to be provided
    Scope & Nature of Services
  21. Change in equity of a company during a period from transactions, events, and circumstances relating to nonowner sources
    Comprehensive Income
  22. Used to measure and report financial statements that are relevant and representationally faithful
    Accounting Standards
  23. Creditors, Investors, Employees, Suppliers, Governments, Communities
    Stakeholders
  24. Establishes GAAP
    FASB
  25. Extensive narrative discussion and quantitative analysis from the company’s managers.
    Management Discussion & Analysis
  26. International Financial Reporting Standards
    IFRS
  27. Members should exercise sensitive professional and moral judgments in their activities.
    Responsibilities
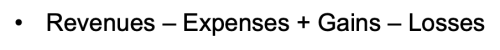
  28. Revenues – Expenses + Gains – Losses
    Net Income
  29. Has legal authority to prescribe accounting principles and reporting practices for all corporations issuing publicly traded securities within the U.S. capital markets.
    Securities and Exchange Commission (SEC)
  30. A member should be objective and free from conflicts of interest in discharging professional responsibilities
    Objectivity & Independence
  31. International Accounting Standards Board
    IASB
  32. Assets = Liabilities + Shareholders’ Equity
    Accounting Equation
  33. Identify significant emerging accounting issues that it feels the FASB should address.
    Emerging Issues Task Force
  34. Generally Accepted Accounting Principles
    GAAP