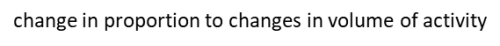(Print) Use this randomly generated list as your call list when playing the game. There is no need to say the BINGO column name. Place some kind of mark (like an X, a checkmark, a dot, tally mark, etc) on each cell as you announce it, to keep track. You can also cut out each item, place them in a bag and pull words from the bag.
1
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
An example of a step-wise cost
Add/Drop a Sales Region
= (expected sales - break even sales) / expected sales
Revised Margin of Safety
= (fixed costs + target income) / contribution margin ratio
Dollar Sales at Target Income
=(expected sales - break-even sales) / expected sales
Margin of
Safety (in percent)
Costs that do not change when the volume of activity changes (within a relevant range)
Fixed Costs
This is what is left over to cover fixed costs after sales.
Contibution Margin (Definition)
=contribution margin per unit / selling price per unit OR = contribution margin / sales
Contribution Margin Ratio
=(fixed costs + target income) / contribution margin per unit
Unit Sales at Target Income
An example of a mixed cost
Maintenance
An example of a variable cost
Shipping
Costs that change in proportion to changes in volume of activity
Variable Costs
= fixed costs / contribution margin per unit
Break-Even Point in Units
Revised Break-Even Point in Do
An example of a step-wise cost
Add/Drop a Warehouse
= revised fixed costs / revised contribution margin ratio
Revised Break-Even Point in Dollars
= fixed costs / contribution margin ratio
Break-Even Point in Dollars
An example of a fixed cost
Property taxes
= selling price per unit - varaiable costs per unit
Contribution Margin Per Unit
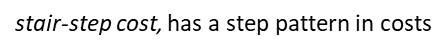
a.k.a. stair-step cost, has a step pattern in costs such as adding a shift of workers
Step-Wise Costs
A planning method that includes predicting the volume of activity, the costs incurred, sales earned, and profits received
Cost-Volume-Profit (CVP) Analysis
Costs that include both fixed and variable cost components.
Mixed Costs
An example of a fixed cost
Straight-Line Depreciation